

The Anthropic IPO docs leaked and revealed what everybody suspected: they are in the business of selling $2 for $1. They are bleeding money and need to get more cash.
The metrics aren’t great if you look at them as a SaaS business:
revenue is $5B+ but they company posted $8B loss in 2025
~25% of the revenue is concentrated on two customers
most customers have no commitments and can leave whenever
The stories surrounding the IPO isn’t great either
Founders want 51% voting power despite owning 2% of the actual shares
Anthropic fed the AI doomer narrative ; an employee worked with a PR agency to tell the world that “AI is not safe and the US should regulate it”. It seems a desperate move to be regulated and control the market.
These elements make it hard to justify a $2T valuation (e.g. equal to Amazon).
I suspect the IPO data and the surrounding stories leaked to get the market sentiment. Anthropic is losing traction, quickly. From April 2026 to August 2026, the market share of open-weight models on Vercel rose from 13% to 56%+. The new reality is that open-weight models will have a larger market share than closed ones. And the reason is simple: open-weight models provide similar value at a fraction of the cost. Why would customers stay with Anthropic if they have no incentive or commitment?
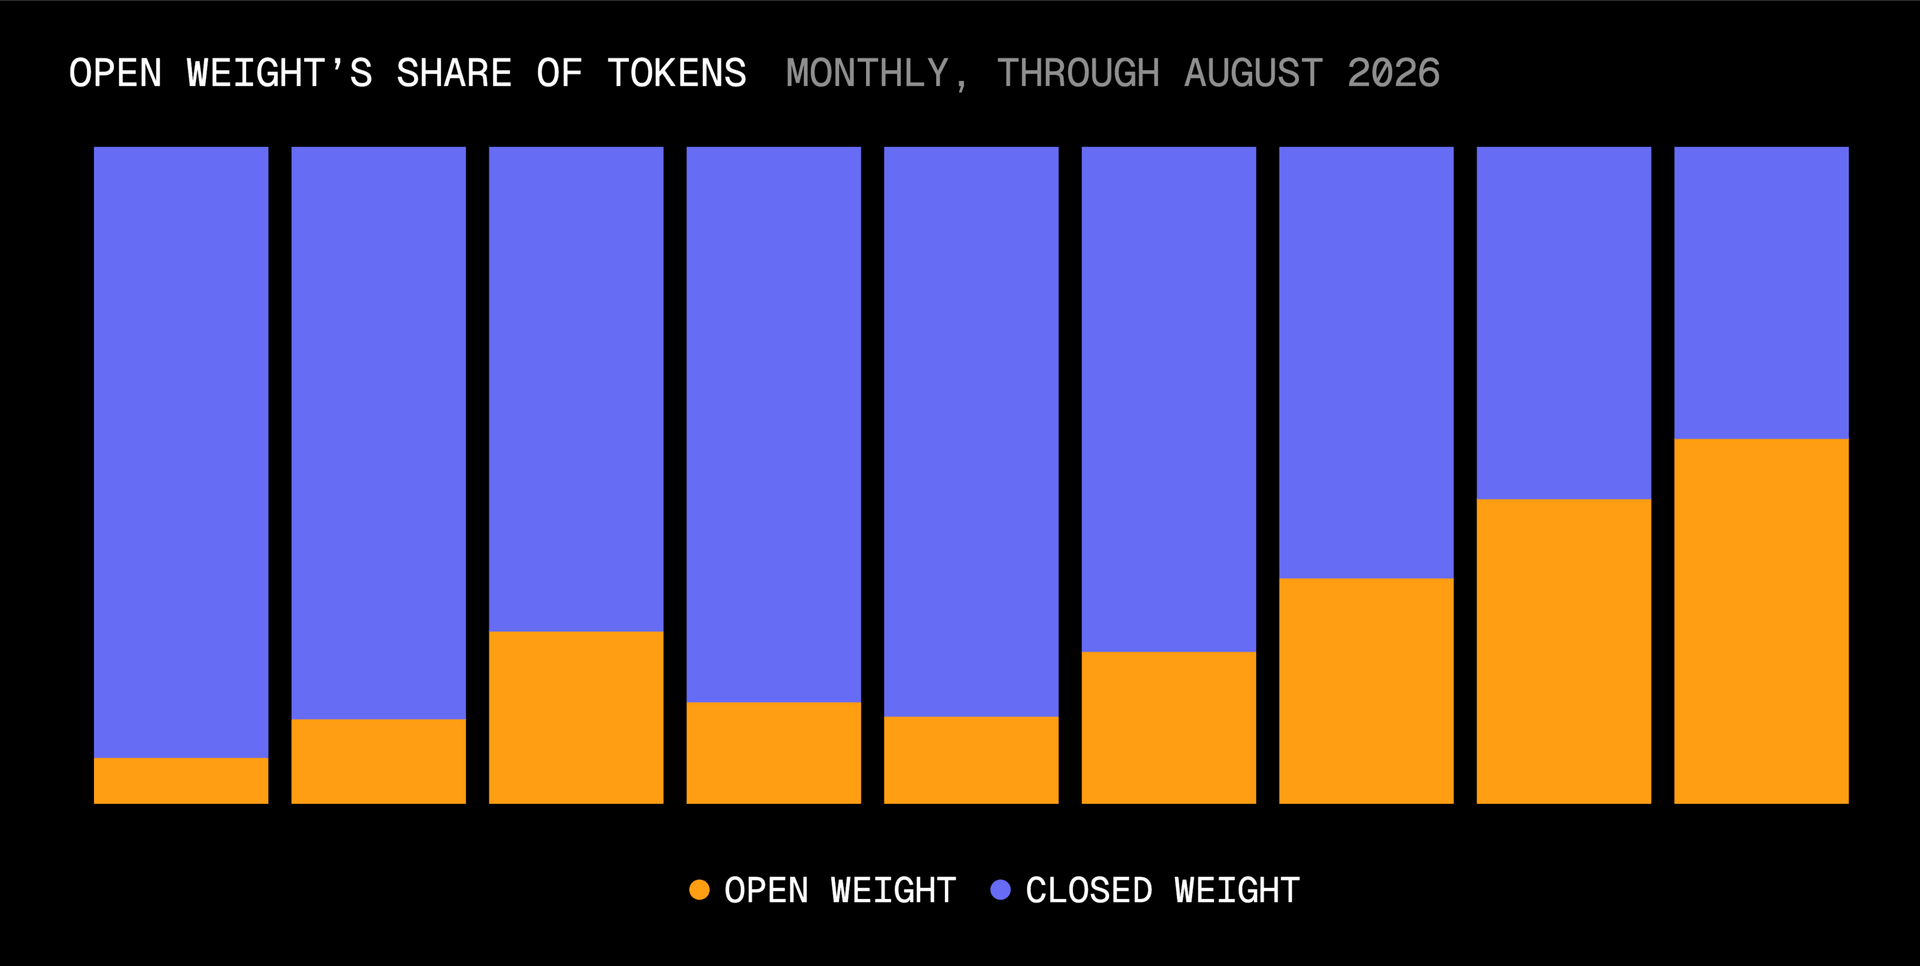
Anthropic is facing real threats and is probably testing the water for a potential IPO. If they wait too long, they will no longer have enough traction to justify a $2T valuation.